

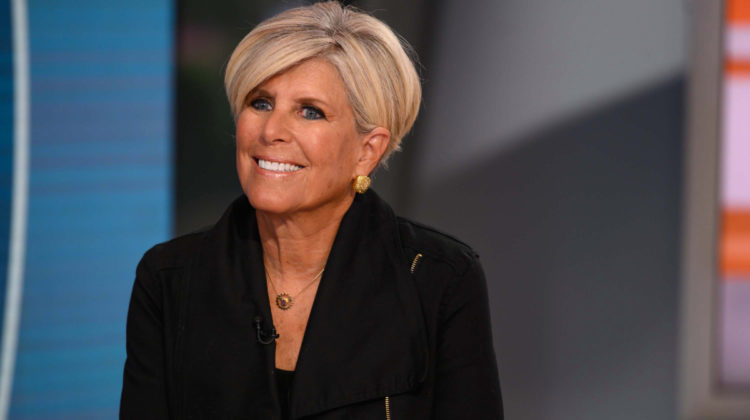
SUZE Orman has warned Americans to check their workplace retirement plans now – or face poverty in older years.
The financial expert urged her followers on Twitter to check how much they’re putting into their plans – as they might not be saving enough to comfortably retire.
Depending on where you work, your company might have a retirement plan in place for employees.
These plans aim to help you save into your pension – and in some cases, your employer will make a contribution too.
The amount you could get from your employer will vary from company to company, but it means that you can boost your savings for the future.
If you’ve started a new job in the past few years, you were likely “auto-enrolled” in your workplace’s retirement plan.
But if you didn’t specify how much you wanted to contribute each month, you would’ve been given a default rate.
Suze said that this default rate is usually set at 4% or even less – which she added was too low to retire on.
She said: “If you were auto-enrolled, the default rate is typically way too low. Many plans start at 4% or less.
“At a minimum you want to save at least 10% of your salary.”
Suze said it’s important to save as much as possible for your later years, as you could face big bills to cover.
She previously said a 65-year-old couple retiring today would need a whopping $300,000 to cover their out-of-pocket health care for the years ahead.
What is a workplace retirement plan?
Employers often have workplace retirement plans – but what yours will look like will depend on who your employer is and what they’re offering.
Many workplaces offer 401(k) plans and some might offer traditional pension plans.
A 401(k) plan allows you to dedicate a percentage of your pre-tax salary to a retirement account, and this is sometimes matched by your employer.
While a traditional pension plan means you put money into a plan – which is sometimes matched by your employer – and the cash is then invested by a professional investor.
However, 401(k) plans are now much more common than a traditional pension plan.
Most employees can currently put in $19,500 a year of their own money in a 401k account, excluding employer contributions.
However, workers who are older than 50-years-old are eligible for an extra catch-up contribution of $6,500 in 2020 and 2021.
The current limit on total employer and employee contributions is $57,000, or 100% of employee compensation (a maximum of $285,000), whichever is lower.
For workers age 50 and up, the base limit is $63,500.
How do I join and how do I boost my contribution?
You’ll likely be automatically enrolled into your company’s workplace pension plan when you joined your new job.
But like Suze says, unless you specify how much you want to contribute, you might not be putting enough away.
If you want to boost how much you’re stashing away – and to check that you’ve been enrolled in a scheme – then contact your HR department.
You should also check your payslip to see how much you’re putting away.
There are a bunch of different retirement plans available – check out the Labor Department website for more information.
Suze Orman recently also revealed how to get a free $100 cash bonus by saving money for 12 months.
Plus, she’s urged parents not to “waste” child tax credit payments of up to $300 with her five top tips.
We round up eight ways to earn free money, including reward websites and 401k boosts.